Stolen Bike Insurance Coverage
Does Renters Insurance Cover a Stolen Bike?
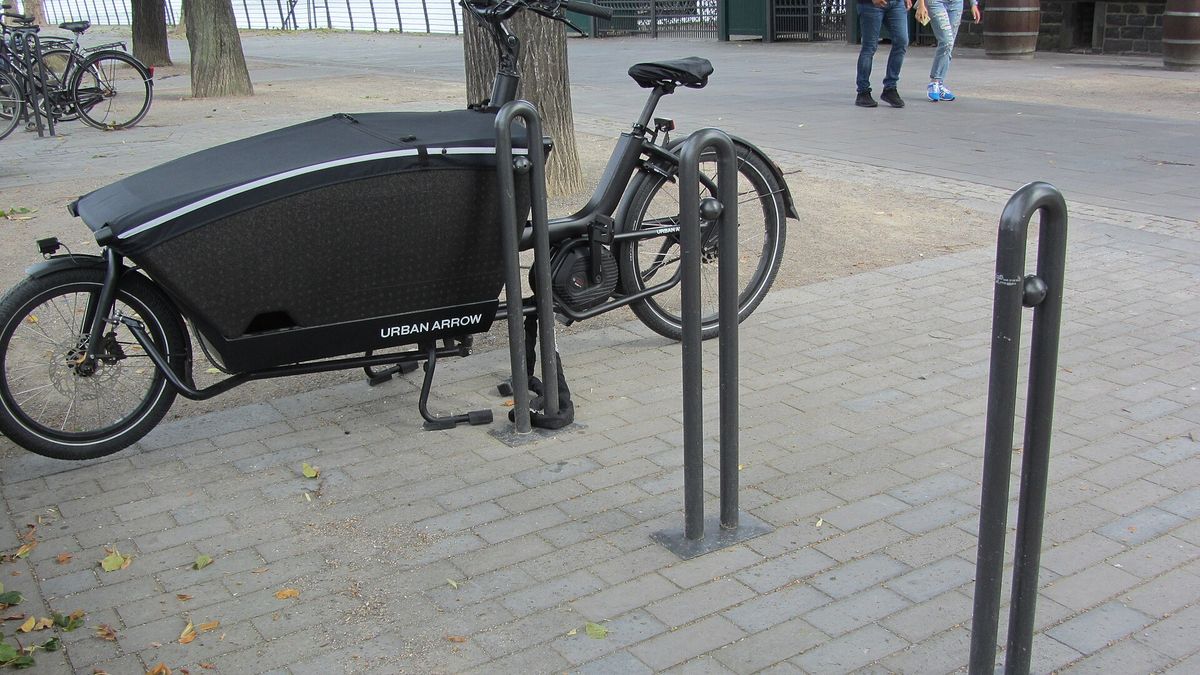
Did someone steal your bicycle? Renters insurance can help, but the exact benefit depends on where the theft happened, and the policy’s terms. As a starting point, theft of the bike as personal property may be covered. But the payout depends on your policy’s deductible, the theft location, and whether the coverage is replacement cost or actual cash value.
Where the Bike is Covered
Standard renters insurance covers bicycle theft. The bike must fall under the policy’s definition of personal property. Renters insurance can cover theft of a bike from a storeroom, a bike rack, or the street. Thief lifts the bike from a garage or storage unit? The bicycle might still be covered. A bike stolen from a locked outdoor rack at work or from a car parked at the grocery store may be covered.
How Much Gets Paid
A payout with renters insurance is not a dollar-for-dollar reimbursement of a bike’s full value. A deductible first reduces the reimbursement by the amount stated in the policy. Once the deductible subtracts out, the reimbursement may be limited by the policy’s sub-limits. And sub-limits can be a big issue. For a stolen bike worth more than the sub-limit, the owner is stuck picking up the rest of the difference.
Then, there’s the depreciation issue. Payouts are made under either actual cash value coverage or replacement-cost coverage. Actual cash value subtracts depreciation from the pre-theft value. Replacement-cost coverage will cover the full cost of a new bike of the same quality.
This means a stolen bike will pay a bit more under replacement-cost coverage versus ACV coverage. The extra cost could be meaningful: if theft hits a $1,500 bike that’s a few years old.
What the Insurer Will Ask For
Filing a claim with a stolen bicycle works differently from registering an auto theft.
The first step usually is to file a police report, unless local law enforcement has a different local protocol. A police report helps those who submit bike-theft claims. Especially the serial number, which owners who want to verify ownership later would have only on their receipt. Renters are usually told to also gather photos and any available receipts, and to check their policy declarations page, which lists deductibles and any item limits.
E-bikes and Special Coverage
Some riders may also want to check their renter policy for electric bikes. USAA says e-bikes may be excluded from the standard renters insurance policy. If so, owners may need a specialty insurance plan from a cycle shop or a standalone e-bike operator. That can be an additional monthly expense, but one that’s worth the extra cost if a lost bike represents a major loss.
Owners of expensive bicycles may also want to schedule their bike as personal property. Worth checking the doc on that, as scheduling may not change how the bike sub-limit is figured.
##
Sources consulted. GEICO · Nationwide · USAA · Insurify